
Written by Jonathan
Fintech is literally eating traditional banking in Nigeria and across Africa. 2018 to 2026, it went from “transfer app” to full bank replacement.
*1. Why Fintech Is Growing So Fast*
**Factor** **What’s Happening** **Example**
**1. Mobile First** 140M+ phone users in NG. Everyone has WhatsApp Opay, Palmpay agents on every street
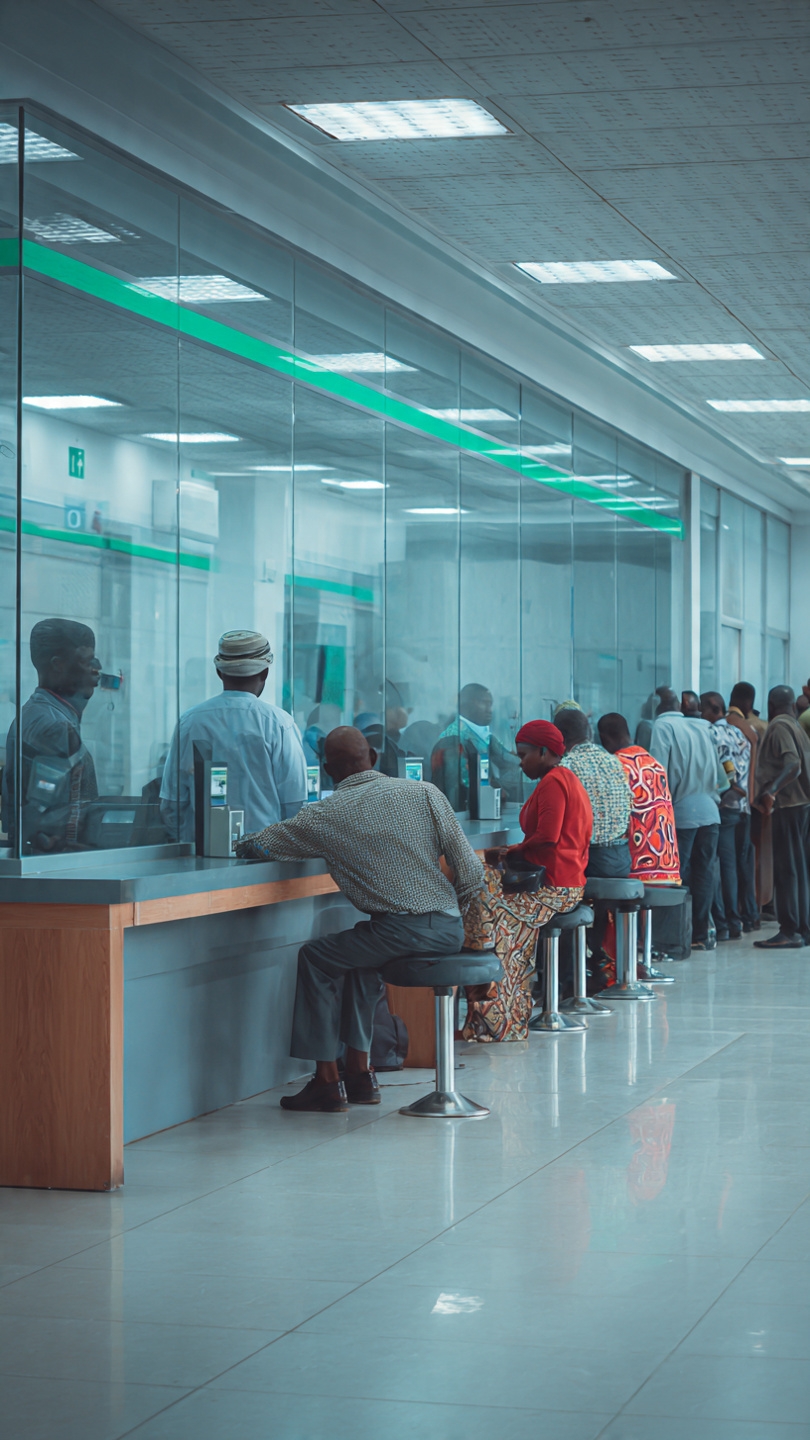
**2. Trust Issues With Banks** Bank queues, network failure, high charges People moved to Kuda, Moniepoint for speed
**3. Youth + Internet** Gen Z don’t go to bank. They do everything on app 70% of fintech users are 18-35
**4. CBN Policies** Cashless policy, Naira redesign, Agent banking Forced people to try fintech
**5. Low Barrier** BVN + Phone number = Account in 2 mins No proof of address, no minimum balance
**6. Funding** $2B+ invested in African fintech 2021-2024 Investors see Africa as next big market
*2. Key Players Driving Growth in Nigeria 2026*
*Tier 1: The Big 4*
1. *Opay* – Agents everywhere. ₦0 transfer. Bill payments. POS king
2. *Palmpay* – Cashback, data, agents. Huge in PH markets
3. *Moniepoint* – Business banking + POS. “Bank for SMEs”
4. *Kuda* – Digital bank. No fees. Savings + Spending
*Tier 2: Rising Fast*
– *Fairmoney* – Loans + Banking
– *Carbon* – Loans + Bills + Cards
– *ALAT by Wema* – First digital bank by traditional bank
– *Sparkle* – Lifestyle + Business banking
– *Flutterwave, Paystack* – Powering businesses behind the scenes
*3. What Fintechs Are Doing That Banks Aren’t*
1. *Instant Everything* – Account opening 2 mins. Loans in 5 mins. Transfers in seconds
2. *No Wahala* – No queue, no “go and come tomorrow”, no ridiculous charges
3. *Agent Network* – Opay/Palmpay/Moniepoint POS agent on every corner in PH
4. *Credit Access* – Fairmoney, Carbon give ₦5k – ₦1M loans with just BVN
5. *Bundled Services* – Save, invest, pay bills, buy airtime, insurance in 1 app
6. *API for Businesses* – Paystack/Flutterwave let any business collect payment online
*4. The Numbers Don’t Lie*
1. *Users*: 50M+ fintech users in Nigeria as of 2026
2. *Transactions*: Fintechs processed ₦60T+ in 2025
3. *POS Agents*: 2.5M+ agents nationwide. More than bank branches
4. *Investment*: Nigeria got 70% of all fintech funding in Africa 2021-2024
*5. Challenges Fintechs Are Facing Now*
1. *Fraud + Scams* – Account takeover, fake POS. CBN is getting strict
2. *Regulation* – CBN keeps changing rules. KYC, withdrawal limits
3. *Profitability* – “₦0 transfer” is not sustainable. Now they’re adding fees
4. *Network Downtime* – When NIBSS is down, everything stops
5. *Trust* – People still keep big money in GTB/UBA. Fintech for daily spending
6. *Competition* – Too many fintechs fighting for same customers
*6. What This Means For You*
*As a Consumer:*
– Lower fees, faster service, but be careful with scams
– Spread money: Salary in bank, daily spending in fintech
*As a Business Owner:*
– Accept Opay/Palmpay/Moniepoint transfers. Customers prefer it
– Use Paystack/Flutterwave to collect online payments
– Get business loans faster from Moniepoint/Fairmoney
*As Someone Looking For Opportunity:*
1. *Fintech Agent* – ₦50k – ₦500k/month from transfers + bills
2. *Build For Fintech* – Developers, Designers, Customer support
3. *Sell To Fintech Users* – Most customers are 18-35 and spend online
*7. What’s Next: 2026-2028 Trends*
1. *AI Banking* – Chatbots that advise you on spending/saving
2. *Embedded Finance* – Bolt, Jumia, Shoe stores offering “Buy now pay later”
3. *Cross-border* – Send money to Ghana, Kenya directly from app
4. *Bank-Fintech Partnership* – Banks buying fintechs instead of fighting them
5. *Regulation* – CBN will license fewer, bigger players
*Bottom Line*
*Fintech won because it solved pain: Speed, Access, No Stress*
Traditional banks are now copying them. But the fintechs that survive will be the ones who make profit, not just growth.
The next 3 years = Less hype, More real banking.
PEOPLE ASK, DOES MAJOR FINTECH HAS DEPOSIT OFFICE???
Yes, but it’s not automatic. In Nigeria, CBN doesn’t just give any fintech the right to “hold deposits” and open offices/branches.
*1. How Fintechs Get Deposit-Taking License*
CBN upgraded many fintechs in *January 2026* to “national status”. That means they can now operate nationwide instead of just state/unit level.
To legally hold customer deposits and have offices, a fintech needs 1 of these CBN licenses:
**License Type** **What It Allows** **Capital Requirement 2026** **Examples**
**1. Microfinance Bank MFB** Hold deposits, give loans, open branches/offices **₦5 billion** for National MFB Sycamore MFB, Moniepoint MFB
**2. Mobile Money Operator MMO** Hold customer funds, operate wallets/e-money **₦2 billion** OPay, PalmPay
**3. Switching/Processing** Route payments, settlements. No direct deposits **₦2 billion** Flutterwave, Paystack, Remita
*Key point*: “PSP licence is no digital banking licence”. If you just have a Payment Service Provider license, you _cannot_ take deposits. You must partner with a bank.
*2. What The 2026 Upgrade Changed*
1. *National Licence* – Opay, Moniepoint, Kuda, PalmPay, Paga got national status. Before they were restricted to unit/tier/state.
2. *Physical Presence Required* – CBN stressed nationally licensed FinTechs and MFBs _must_ maintain physical presence in key areas.
Why? To resolve disputes and serve informal customers who need face-to-face.
3. *Stricter Rules* – Higher capital, AML monitoring, data localisation by Jan 1 2027, UBO disclosure.
*3. What “Deposit Office” Actually Means For Fintechs*
With MFB or National license, they can:
1. *Accept deposits directly* – No need for 3rd party bank. Example: Sycamore can now let 400,000+ customers save/hold funds
2. *Connect to NIBSS directly* – Faster settlement, lower fees
3. *Open Branches/Agent Offices* – Physical offices for complaints + cash-in/cash-out. This is why you now see Opay/Palmpay/Moniepoint offices everywhere in PH.
CBN’s goal: Use FinTechs to tackle “cash-outside-banks” problem.
*4. Important CBN Rules in 2026*
1. *No takeover of banks* – CBN says FinTechs will not take over bank roles. Banks still do intermediation.
2. *Compliance First* – ₦1 billion penalty was given to Moniepoint and Opay in 2024 for KYC issues
3. *Data Must Stay in Nigeria* – All payment data must be stored locally by Jan 1, 2027
4. *No Digital Bank Licence Yet* – CBN has no plans to roll out a dedicated digital banking licence. For now it’s MFB + MMO route.
*5. Bottom Line For You*
*To hold deposits + have offices, a fintech must:*
1. Get *MFB License ₦5B* OR *MMO License ₦2B*
2. Meet CBN compliance: KYC, AML, data localisation, physical branches
3. Operate under national license if they want to serve all of Nigeria
That’s why Opay, Moniepoint, Kuda, PalmPay now act like “banks” but are still regulated as MFBs/MMOs.
SO IS OPAY NOW A COMMERCIAL BANK???
*No, Opay is NOT a commercial bank yet*
*What Opay is in 2026*
Opay operates as a *Microfinance Bank MFB + Mobile Money Operator MMO* with a *national licence*.
CBN upgraded Opay, Moniepoint, Kuda, PalmPay and Paga to *national status* on Jan 26, 2026.
*Key Differences*
**Thing** **Commercial Bank** **Opay – MFB/MMO**
**License** Commercial Banking License MFB + MMO National License
**Deposit** Can take unlimited deposits Can take deposits within MFB/MMO rules
**Capital** ₦200 Billion minimum **₦5 billion** for National MFB
**Services** Loans, FX, International, Corporate banking Payments, Deposits, Loans, Agent banking
**Branches** Full branches nationwide Physical presence/offices required
*What Changed For Opay*
1. *Can take deposits directly* – Before they had to partner with banks. Now they hold customer funds in a regulated framework
2. *Connect to NIBSS directly* – Faster transfers, lower fees
3. *Physical offices* – CBN requires national FinTechs/MFBs to maintain physical presence for disputes and cash services
4. *Stricter regulation* – Higher capital ₦5B, KYC/AML, data localisation
*Important Note From CBN*
CBN said FinTechs will *not take over bank roles*. Banks still do intermediation. And CBN has *no plans to roll out a dedicated digital banking licence*.
So Opay is now a *national MFB*, not a commercial bank like GTB, Zenith, or Access.
Think of it this way:
*Commercial Bank* = Full bank
*Opay* = Digital MFB with national reach + agent network
That’s why Opay can give you account number, savings, and loans, but some big corporate services still go through partner banks.
We hope you have been informed… See you again
